My Achievements in WordPress
I am so surprised and proud to see that my blog has reached more than 150 countries!!
From Shipwrecks to Safety Nets: The Origin of Insurance
Insurance did not begin in a boardroom. It began with fear.
Fear of losing a ship.
Fear of fire destroying a home.
Fear of a family starving after the death of the breadwinner.
And human beings eventually realized something powerful:
“One person alone may be ruined by disaster. But if many people share the risk together, nobody has to be destroyed.”
That simple idea became insurance.
The Earliest Form of Insurance — Ancient Traders
Thousands of years ago, merchants in places like ancient China and Babylon carried silk, spices, and grain across dangerous rivers and seas.
Ships sank. Bandits attacked. Storms destroyed cargo.
If one merchant lost everything, his family could become poor overnight.
So traders created a system:
- Instead of putting all goods on one ship, they spread cargo across many ships.
- Groups of merchants contributed money into a common pool.
- If one person suffered a loss, the pool compensated him.
This was the seed of insurance.
One of the earliest written examples appears in the ancient Code of Hammurabi in Babylon around 1750 BCE. A merchant taking a loan for a sea voyage could pay an extra fee so the lender would cancel the debt if the shipment was lost.
That extra fee was basically an early insurance premium.
The Story Changes in London
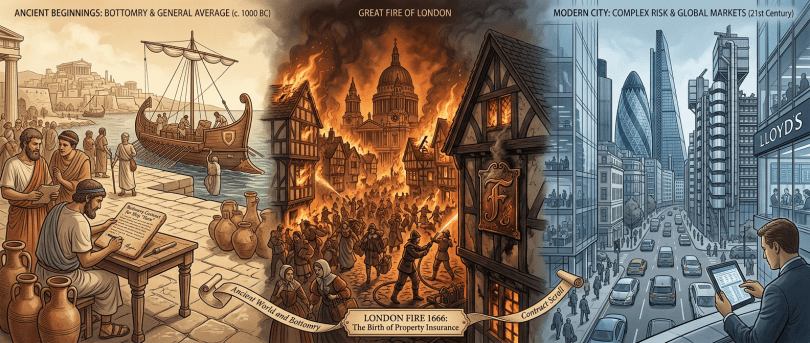
The modern insurance industry truly took shape in 17th-century London.
Back then, London was crowded with wooden houses, candles, fireplaces, and narrow streets.
In 1666, disaster struck:
The Great Fire of London burned for four days.
More than 13,000 houses were destroyed.
People suddenly understood:
- Fire can wipe out entire neighborhoods.
- Rebuilding alone is impossible for most families.
After this tragedy, businesses began offering fire insurance. Homeowners paid regular amounts of money, and if their house burned down, the insurer helped cover the loss.
Some companies even created private fire brigades. Homes insured by a company displayed metal fire marks outside their houses so firefighters knew whom to help.
Shipping and the Birth of Big Insurance
At the same time, global trade was booming.
Ships traveled between Europe, Asia, and the Americas carrying tea, cotton, gold, and spices. But sea travel was extremely risky.
In a coffee house owned by Edward Lloyd, ship owners, merchants, and wealthy investors gathered to discuss voyages.
Investors would agree to cover portions of a ship’s risk in exchange for payment.
That coffee house eventually became Lloyd’s of London — one of the most famous insurance institutions in history.
The word “underwriter” comes from this practice because investors literally wrote their names under the risk agreement.
Life Insurance: A Different Kind of Protection
Eventually people asked a harder question:
“What happens to a family when a person dies?”
This led to life insurance.
At first, many people thought it was strange or even immoral to place money around death. But over time, society saw its value.
Life insurance became a way to protect widows, children, and families from financial collapse.
As cities industrialized during the 1800s:
- factory accidents increased,
- disease spread rapidly,
- workers faced dangerous conditions.
Insurance expanded into:
- health insurance,
- accident insurance,
- workers compensation,
- automobile insurance,
- business insurance.
Why Insurance Became Powerful
Insurance works because not everyone suffers loss at the same time.
For example:
- out of 10,000 homes, only a small percentage may burn down each year,
- out of millions of drivers, only some will have accidents,
- many people pay premiums, but only a smaller group files claims.
This creates a financial safety net.
At its best, insurance allows people to:
- start businesses,
- buy homes,
- travel,
- build factories,
- recover after disasters,
without being completely ruined by one bad event.
Modern economies could not function without insurance.
Banks often will not issue mortgages without homeowners insurance. Businesses cannot operate major projects without liability coverage. Airlines, hospitals, shipping companies — all depend on insurance systems.
The Human Side of Insurance
At its core, insurance is really about collective survival.
It says:
“We cannot stop bad things from happening. But we can prevent one tragedy from destroying a person’s entire future.”
That is why the concept survived for thousands of years and became one of the foundations of modern civilization.
Marianne Williamson
Marianne Williamson is a prominent author, lecturer, and public figure known for her work in spirituality, personal growth, and emotional healing. Over several decades, she has built a wide audience through her books, teachings, and more recently, her involvement in U.S. politics.
Her rise to prominence began with A Return to Love, a work based on the principles of A Course in Miracles. The book emphasizes the idea that love and fear are the two fundamental forces shaping human behavior, and that choosing love leads to deeper healing and fulfillment. This theme runs consistently through her later works, including Healing the Soul of America and The Law of Divine Compensation. Her writing often blends spirituality with practical reflections on relationships, self-worth, and purpose.
Beyond her professional work, Williamson’s personal life reflects both independence and complexity. She was born in Houston, Texas, to parents Samuel Williamson, an immigration lawyer, and Sophie Ann Williamson. She grew up in a Jewish family, which influenced her early exposure to spiritual and philosophical ideas.
In terms of education, she attended Pomona College in California, where she studied theater and philosophy, although she did not complete her degree. Like many influential figures outside traditional paths, her impact came more from her independent exploration and teaching than formal credentials.
Her personal relationships have been relatively private. She was briefly married in her early adulthood, but the marriage ended quickly. She has one daughter, India Emmaline Williamson, who has occasionally been mentioned in her public life. Williamson has often spoken about the challenges and growth that come with balancing personal development, motherhood, and a public career.
What makes Williamson distinct is how she has extended her ideas beyond books into public discourse. She ran for the Democratic presidential nomination in 2020 and again in 2024, bringing a message centered not just on policy, but on moral and emotional renewal. While critics questioned the practicality of her approach, supporters appreciated her willingness to address deeper human concerns often ignored in politics.
Here’s the grounded takeaway: Marianne Williamson’s life and work don’t fit neatly into conventional categories. She is not a traditional academic, nor a typical political figure. Her influence comes from her ability to articulate emotional and spiritual struggles in a way that resonates with many people. Whether or not one agrees with all her ideas, her work challenges people to reflect on how fear, love, and personal responsibility shape both individual lives and society as a whole.
Interview Tips for someone with 15 plus years of experience
The Core Problem to Avoid
After 15–20 years, candidates don’t get rejected for lack of knowledge.
They get rejected for:
👉 under-positioning themselves
Meaning:
- Sounding like a mid-level executor
- Not showing ownership
- Talking tasks instead of impact
1. Own the conversation from the first minute
Mistake:
- “I’m not sure who reached out…”
Why it hurts:
Signals:
- Lack of awareness
- Passive mindset
Better:
Start with clarity and control:
“I was approached regarding a BA role in insurance, and based on my experience in policy admin and data projects, I believe I align well. Happy to walk you through my background.”
👉 Senior candidates anchor the conversation early
2. Never lead with your gaps
Mistake:
- “I haven’t worked in reinsurance”
- “Not sure”
Why it hurts:
You are telling them why NOT to hire you
Better approach:
👉 Strength → Then gap → Then confidence
“I’ve worked extensively in insurance systems and data, including reinsurance-related flows. While I haven’t worked exclusively on reinsurance platforms, I understand the concepts and can ramp up quickly.”
👉 You control the narrative—not your limitations
3. Stop explaining everything—start structuring answers
Mistake:
- Long, wandering answers
- No clear point
Why it hurts:
At senior level:
👉 Clarity = competence
Use this structure every time:
Context → Role → Action → Outcome
If you miss this:
👉 You sound experienced but not sharp
4. Don’t say “I don’t know” the wrong way
Mistake:
- “Not sure”
- “I’m assuming”
Why it hurts:
Shows lack of confidence, not just lack of knowledge
Better:
“I haven’t worked directly on that, but based on my understanding…”
Then reason it out.
👉 Senior people are judged on thinking ability, not just answers
5. Don’t trivialize your learning curve
Mistake:
- “I can learn it in 1 day”
Why it hurts:
Sounds unrealistic and junior
Better:
“Given my experience in similar domains, I’m confident I can ramp up quickly and contribute meaningfully.”
👉 Show confidence, not overconfidence
6. Speak like a senior, not a task executor
Mistake:
- Talking about:
- Jira tickets
- User stories
- Templates
Why it hurts:
That’s execution-level language
Upgrade your language:
Instead of:
“I created Jira tickets”
Say:
“I drove requirement breakdown and ensured clarity across development and QA teams”
👉 Same work, different positioning
7. Show decision-making, not just involvement
Mistake:
- “I worked on…”
- “I was involved in…”
Why it hurts:
Sounds like support role
Better:
“I led…”
“I owned…”
“I was responsible for…”
👉 After 20 years, you are expected to drive, not assist
8. Avoid generic textbook answers
Mistake:
- “Agile is flexible…”
- “We work in sprints…”
Why it hurts:
Sounds rehearsed and shallow
Better:
“In Agile, my focus is ensuring clear user stories and acceptance criteria so dev and QA don’t lose time in rework.”
👉 Practical answers > textbook definitions
9. Handle domain gaps strategically
If you lack experience in a specific area:
Don’t:
- Apologize
- Over-explain
- Panic
Do:
- Map your experience
- Show transferability
👉 “I haven’t done X directly, but I’ve done A, B, C which are closely related”
10. Be crisp—brevity is power
Mistake:
- Talking too much
- Trying to prove everything
Why it hurts:
Senior people are expected to:
👉 Communicate clearly under time pressure
Rule:
- 2–3 minutes per answer
- Then stop
One Powerful Mindset Shift
Most candidates with 20 years think:
“Let me explain everything I’ve done”
That’s wrong.
You should think:
“Let me show why I am worth hiring in 30 minutes”
Final Truth
At this level:
- Your experience gets you the interview
- Your communication gets you the job
If you want, I can help you turn this into a very short checklist (like 5 rules) that he can quickly review before every interview.
Check this Bed Bug Infested Cities before travelling
Every year pest-control companies like Orkin and Terminix publish rankings of the most bed-bug-infested cities in the United States based on the number of treatments they perform in homes, hotels, and apartments. The 2025 list from Orkin analyzed service data from May 2024–May 2025 across U.S. metro areas.
Below is the Top 50 most bed bug–infested cities in America (2025).
“Which city and state do you live in? Have you ever encountered bed bugs in your home, hotel, or travels? Share your experience in the comments.”
50 Most Bed Bug–Infested Cities in America (2025)
Top 10
- Chicago, Illinois
- Cleveland, Ohio
- Detroit, Michigan
- Los Angeles, California
- Indianapolis, Indiana
- Washington, D.C.
- Grand Rapids, Michigan
- Columbus, Ohio
- Champaign, Illinois
- Milwaukee, Wisconsin
11–20
- Baltimore, Maryland
- Pittsburgh, Pennsylvania
- Cincinnati, Ohio
- Denver, Colorado
- New York, New York
- Flint, Michigan
- Atlanta, Georgia
- St. Louis, Missouri
- Charleston, West Virginia
- Cedar Rapids, Iowa
21–30
- Davenport, Iowa
- Youngstown, Ohio
- Raleigh, North Carolina
- Dallas, Texas
- Philadelphia, Pennsylvania
- Omaha, Nebraska
- South Bend, Indiana
- Richmond, Virginia
- Knoxville, Tennessee
- Greenville, South Carolina
31–40
- Norfolk, Virginia
- Charlotte, North Carolina
- Peoria, Illinois
- Toledo, Ohio
- Hartford, Connecticut
- Dayton, Ohio
- Nashville, Tennessee
- Tampa, Florida
- Houston, Texas
- Greensboro, North Carolina
41–50
- Kansas City, Missouri
- Minneapolis, Minnesota
- Lansing, Michigan
- Boston, Massachusetts
- Seattle, Washington
- Phoenix, Arizona
- San Francisco, California
- Orlando, Florida
- Salt Lake City, Utah
- Portland, Oregon
Key Insights
- Chicago has been ranked #1 for five consecutive years.
- Many cities in the Midwest (Ohio, Michigan, Illinois) dominate the rankings.
- Bed bugs spread easily through travel, luggage, hotels, and used furniture.
- Larger cities appear more often because more people = more travel and housing density.
When Leaders Ignore the Iceberg
What the Titanic Teaches Modern Business Leaders About Failure, Risk, and Responsibility
The sinking of the Titanic is often remembered as a maritime tragedy. But for business leaders, it is something more important: a case study in leadership failure, overconfidence, and poor risk management.
The Titanic did not fail because of one iceberg. It failed because of human decisions, flawed systems, and leadership blind spots—problems that still sink organizations today.
1. Overconfidence Is the Enemy of Preparedness
The Titanic was marketed as unsinkable. That belief shaped decisions:
- Speed was not reduced
- Safety precautions were relaxed
- Risks were underestimated
Business parallel:
Companies that believe they are “too big to fail” often ignore warning signs—until it’s too late.
Leadership lesson:
Confidence must be balanced with humility. Strong leaders plan not just for success, but for failure scenarios.
2. Ignored Warnings Are Leadership Failures, Not Information Gaps
The Titanic received multiple iceberg warnings. The problem wasn’t lack of data—it was lack of action.
Business parallel:
Employees raise red flags all the time: declining customer trust, compliance risks, burnout, market shifts. When leadership dismisses these signals, the organization drifts toward crisis.
Leadership lesson:
Good leaders don’t just collect information—they respond decisively to it.
3. Weak Systems Collapse Under Pressure
There were not enough lifeboats. Evacuation plans were unclear. Crew training was inadequate.
Business parallel:
In normal times, weak systems go unnoticed. During crises—economic downturns, lawsuits, cyberattacks—they fail spectacularly.
Leadership lesson:
Strong systems matter more than heroic individuals. Leaders must invest in processes, training, and contingency planning before emergencies occur.
4. Cost-Cutting Without Ethics Creates Hidden Risk
Lifeboats were reduced partly for aesthetics and cost. Regulations were technically met—but barely.
Business parallel:
Cutting corners to boost margins—on safety, compliance, or employee welfare—may look efficient short-term but creates long-term disaster.
Leadership lesson:
Ethical leadership means asking, “What is the real cost of this decision?” not just “Is it legal?”
5. Inequality Worsens Crises
First-class passengers had better access to lifeboats. Third-class passengers were delayed.
Business parallel:
When leaders protect only top performers or executives during crises, morale collapses and trust erodes.
Leadership lesson:
In hard times, fairness matters more than ever. How leaders treat their most vulnerable people defines their legacy.
6. Training Beats Talent in Emergencies
Lifeboats were launched half empty because crews were unsure how to respond.
Business parallel:
Smart teams without preparation panic under pressure. Training—not brilliance—determines performance during crisis.
Leadership lesson:
Leaders must invest in practice, drills, and clarity, not just hiring “talent.”
7. Nature (and Reality) Always Wins
Technology, reputation, and confidence could not override physical reality.
Business parallel:
Markets, customers, and economic forces do not care about brand reputation or past success.
Leadership lesson:
Leaders must respect limits—financial, human, and environmental.
8. Leadership Is Revealed, Not Claimed
Some Titanic leaders froze. Others acted decisively and saved lives.
Business parallel:
Titles don’t create leaders. Crises expose who can make calm, ethical decisions under pressure.
Leadership lesson:
True leadership is action-driven, not position-driven.
9. Preparation Is Invisible—Until It’s Missing
Lifeboats seemed unnecessary until they weren’t.
Business parallel:
Risk management feels like wasted effort—until it becomes survival.
Leadership lesson:
Preparedness is a leadership responsibility, not an optional expense.
10. Disasters Are Chains of Small Decisions
The Titanic didn’t sink because of one error. It sank because of:
- Small ignored warnings
- Minor compromises
- Gradual erosion of caution
Business parallel:
Most corporate failures are not sudden—they are slow, predictable, and preventable.
Leadership lesson:
Pay attention to small problems. They are early warnings, not inconveniences.
Final Takeaway for Leaders
The Titanic didn’t fail because of an iceberg—it failed because leadership underestimated risk, ignored warnings, and trusted reputation over reality.
Modern business leaders who learn from Titanic don’t just avoid disaster—they build organizations that are resilient, ethical, and prepared for uncertainty.
Useful Training Links in New Jersey
Round Valley Reservoir – New Jersey

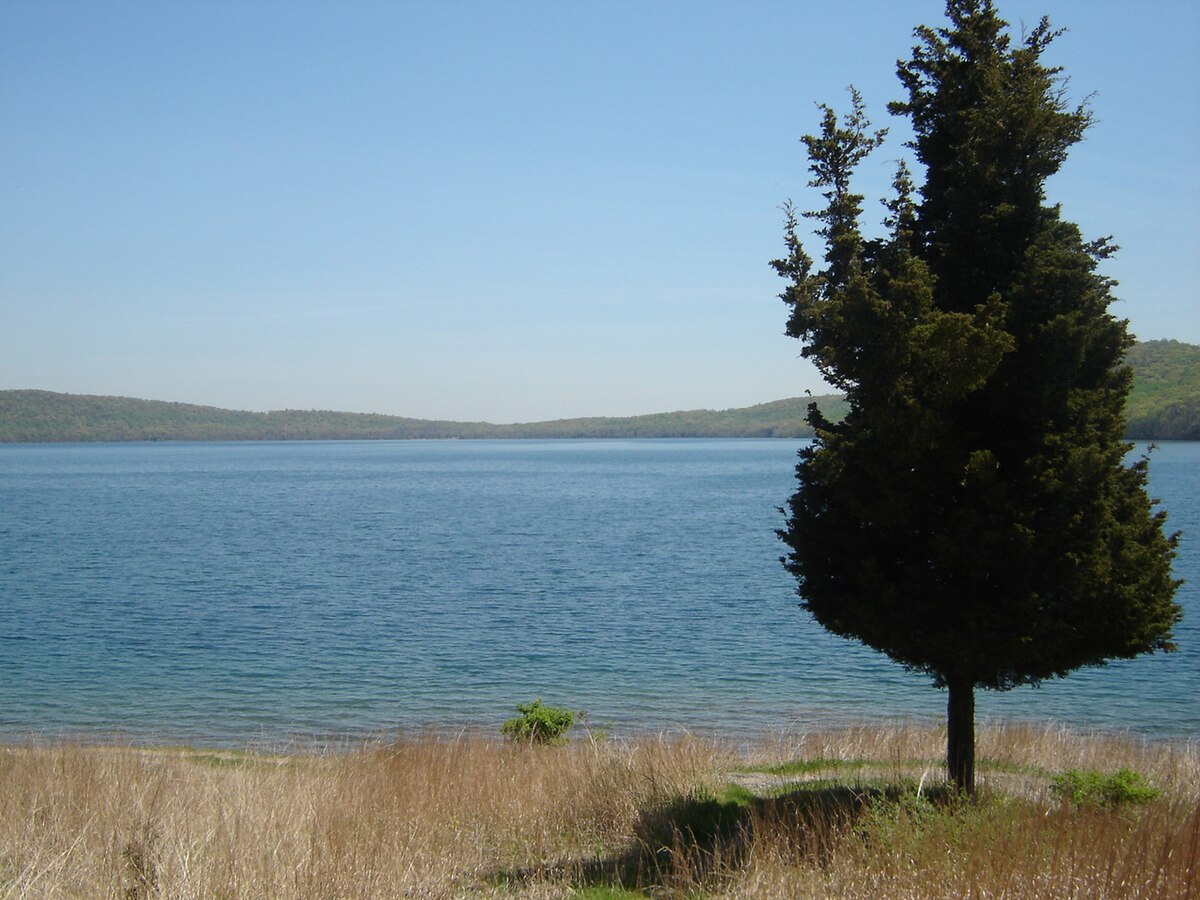
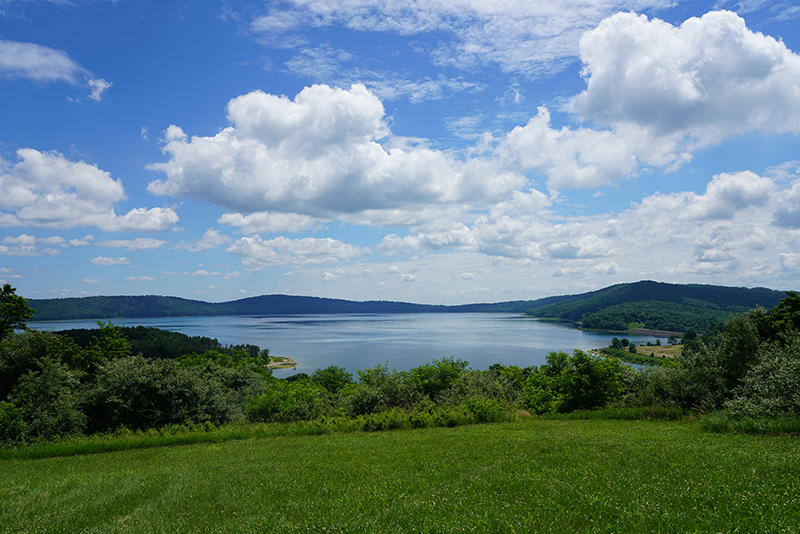
Round Valley Reservoir: A Hidden Gem in Clinton, New Jersey
Nestled in the scenic hills of Hunterdon County, New Jersey, Round Valley Reservoir is a striking combination of natural beauty and recreational opportunity. Known for its deep, clear waters and rugged surroundings, it has become a favorite spot for outdoor enthusiasts across the state.
A Unique Location
The reservoir sits in a valley formed by the surrounding ridges of Cushetunk Mountain. Unlike many lakes in New Jersey, Round Valley is exceptionally deep, reaching nearly 180 feet at its lowest points. This depth, combined with the clarity of its water, gives the lake a vivid blue-green hue that catches the eye of every visitor. The area surrounding the reservoir remains largely natural, with forested trails and hills providing a sense of wilderness within reach of nearby towns.
Origins and Purpose
Round Valley Reservoir was developed in the mid-20th century to meet New Jersey’s growing water needs. Engineers constructed dams that flooded the valley, creating a large storage reservoir capable of holding billions of gallons of water. Today, it continues to serve as an important part of the state’s water supply system, while also providing a sanctuary for wildlife and a place for residents to enjoy outdoor activities.
Recreation Opportunities
One of the reasons Round Valley is so popular is the variety of recreational activities it offers:
- Fishing: Anglers can try their luck with species such as trout, bass, and perch. The lake’s depth allows for thriving fish populations, and it’s well-known among local anglers for producing record catches.
- Boating: Small boats, kayaks, and paddleboards are welcome, though motorized boats are limited to low-horsepower engines to preserve the environment.
- Camping and Hiking: For those seeking solitude, remote camping sites are available, accessible only by foot or boat. Trails wind through the surrounding hills, offering opportunities for hiking, biking, and horseback riding.
- Swimming and Picnicking: A designated swimming beach is open during the summer, and picnic areas provide family-friendly spaces to relax and enjoy the views.
- Winter Activities: In the colder months, visitors often enjoy cross-country skiing, sledding, or ice fishing, weather permitting.
Natural Beauty and Caution
Visitors are often captivated by the lake’s clear waters and scenic landscape, but the depth and open topography mean conditions can change rapidly. Winds can create unexpected waves, so caution is advised for boaters and swimmers. The area’s rugged terrain also makes proper preparation essential for hiking or camping trips.
Why Visit Round Valley?
Round Valley Reservoir is more than just a body of water; it is a place where nature, adventure, and community intersect. Whether you are fishing for trout, exploring the forested trails, or simply enjoying a picnic with a view, the reservoir provides a refreshing escape from city life. Its combination of recreational opportunities and natural splendor makes it one of New Jersey’s most treasured destinations.
For more details click here – https://www.njportal.com/DEP/NJOutdoors/Park/Details?locationId=11
Insurance Exam – New Jersey
Insurance Exam Quick Summary (Numbered Points)
- Irrevocable Beneficiary
- An irrevocable beneficiary designation prevents the policyowner from making any policy changes without the beneficiary’s written consent.
- Adverse Selection
- Adverse selection is the tendency of higher-risk individuals to buy insurance more often than average-risk individuals.
- Consideration (Life & Health Insurance)
- Consideration consists of statements made in the application and the premium paid.
- Insurable Interest
- Insurable interest must exist only at the time of application, not at the time of claim.
- If no beneficiary change occurs, the original beneficiary still receives proceeds.
- Policy Forms Responsibility
- The insurance carrier (insurer) assembles policy forms, riders, and endorsements.
- The producer may deliver the policy but does not assemble it.
- Dividends from Mutual Insurers
- Dividends are not taxable because they are considered a return of excess premium, not income.
- Mutual insurers may overcharge initially and refund surplus.
- Mutual vs Stock Insurers
- Mutual insurer = Participating
- Stock insurer = Non-participating
- Do Not Call Registry
- Insurance sales calls are NOT exempt.
- Political organizations, charities, and surveys are exempt.
- Fair Credit Reporting Act (FCRA)
- Obtaining consumer reports under false pretenses:
- Up to $5,000 fine and 1 year imprisonment (producer)
- Federal maximum fines may reach $10,000 (individual) and $50,000 (corporation)
- Obtaining consumer reports under false pretenses:
- Contract of Adhesion
- Insurance contracts are prepared by the insurer with no negotiation.
- Applicant must accept on a “take it or leave it” basis.
- Rating Service Companies
- Their primary purpose is to determine an insurer’s financial strength.
- Law of Agency
- The producer represents the principal (insurer).
- Agents have actual, implied, and apparent authority.
- The insurer is legally responsible for the agent’s actions.
- Implied Authority
- Unwritten authority assumed necessary to conduct business on behalf of the insurer.
- Group Insurance Enrollment Period
- The enrollment period is a limited time during which eligible members may sign up.
- It cannot exceed four months.
- COBRA Continuation
- Coverage remains the same.
- Premium may increase to 102% of the prior premium.
- Election must be made within 60 days.
- Preferred Provider Organization (PPO)
- Out-of-network care is covered, but at a lower percentage.
- If care is outside the network with no coverage, insured may pay 100%.
- Suicide Clause (Life Insurance)
- If suicide occurs within the stated period:
- Insurer refunds premiums paid minus indebtedness
- No interest is paid
- If suicide occurs within the stated period:
- Group Disability Income Insurance
- Covers non-occupational illnesses and injuries.
- Occupational injuries are covered by workers’ compensation.
- Annuities
- Only the policyowner can surrender an annuity during accumulation.
- Refund annuity returns the remaining value if annuitant dies during payout.
- Fixed Period Option:
- Payments made for a set time
- Beneficiary chooses the time period, not the amount
- If beneficiary dies, remaining payments go to estate or contingent beneficiary
- Indexed Annuities
- Interest is tied to a market index (commonly S&P 500).
- Subject to caps, floors, or participation rates.
- Unearned Premium
- Unearned premium belongs to the insured, not the insurer.
- Alien Insurance Company
- Chartered and organized in a country outside the United States.
- New Jersey Licensing & Compliance
- CE Requirement: 24 hours every 2 years, including 3 ethics hours
- Temporary Certificate validity: 60 days
- Branch office registration: 30 days before opening
- Closing a branch office: Notify within 30 days
- Producer must notify DOBI within 30 days of:
- Address changes
- Administrative actions
- Policy Delivery
- Individual policy or certificate must be delivered:
- At effective date or
- Within 30 days
- Individual policy or certificate must be delivered:
- Medicare Rules
- Medicare qualifying events do NOT include being poverty-stricken.
- Medicare Advantage (Part C) enrollment occurs when eligible for Medicare.
- Medicare Supplement can be canceled for nonpayment.
- If age 65+ and working for an employer with 20+ employees:
- Employer plan is primary
- Medicare is secondary
- Alcoholism Coverage
- Group health-care service contracts must cover treatment for alcoholism.
- Disability Income Insurance
- Designed to replace a portion of income during disability.
- Does not replace full income or pay medical expenses.
- Subrogation
- Allows the insurer to recover money from a third party responsible for the loss after paying a claim.
- Prevents double payment and helps control premiums.

